Retiring in the Philippines is not only about choosing a beautiful island, buying a condominium, or finding a quiet place near the sea.
A successful retirement requires much more practical preparation.
Before making a permanent move, a foreign retiree should think carefully about legal residency, monthly living costs, healthcare, housing, transportation, banking, insurance, family arrangements, and what everyday life will actually look like after retirement.
For many people, the dream begins with warm weather, beaches, good food, and a slower pace of life.
But retirement is not a two-week vacation.
The place you choose must also work on an ordinary weekday when you need to visit a doctor, pay a bill, buy groceries, deal with traffic, renew documents, or simply decide how to spend your day.
The Philippines can be an attractive retirement destination, but the best results usually come from planning first and committing later.
Preparing for Retirement in the Philippines at a Glance
- Visa: Decide which long-term immigration option fits your circumstances
- Budget: Calculate housing, food, utilities, healthcare, transportation, travel, and emergency expenses
- Location: Choose based on your actual lifestyle and healthcare needs, not only scenery
- Housing: Rent first before considering a major property purchase
- Healthcare: Identify hospitals, specialists, insurance options, and emergency arrangements before moving
- Transportation: Decide whether Grab, public transportation, a private vehicle, or a driver suits your lifestyle
- Banking: Plan how you will receive pensions, transfer money, and access funds in the Philippines
- Emergency fund: Maintain enough accessible funds for medical, family, travel, and unexpected expenses
- Property: Understand foreign ownership restrictions before investing
- Family: Consider whether a spouse or dependents will move with you
- Daily life: Think about what you will actually do during ordinary weeks after retirement
- Best advice: Spend several months living in the Philippines before making permanent commitments
Table of Contents
1. Decide Whether the Philippines Fits Your Retirement Lifestyle
The first question should not be: Which city should I retire in?
A better question is:
Is the Philippines actually suitable for the kind of retirement I want?
The Philippines offers many advantages for foreign retirees.
English is widely used, the climate is warm, domestic travel opportunities are extensive, and living costs can be flexible depending on location and lifestyle. Large cities also offer modern condominiums, shopping centers, restaurants, private hospitals, and international services.
But there are trade-offs.
Traffic can be frustrating.
The weather can be hot and humid.
Infrastructure varies considerably.
Government procedures may require patience.
Public transportation and pedestrian infrastructure may not meet the expectations of someone accustomed to highly developed urban systems.
The best retirement destination is therefore not simply the country with the lowest living costs or the most beautiful beaches.
It is the place where your finances, health, personality, family situation, and preferred lifestyle work together.
If you are still deciding whether the country is right for you, see our guide to 12 Reasons Why the Philippines Is One of the Top Retirement Destinations.
2. Understand Your Long-Term Visa Options
Legal residency should be one of the first practical matters to consider.
A foreign national cannot simply assume that arriving as a tourist provides a permanent retirement solution.
The Philippines offers different immigration options depending on the retiree’s circumstances.
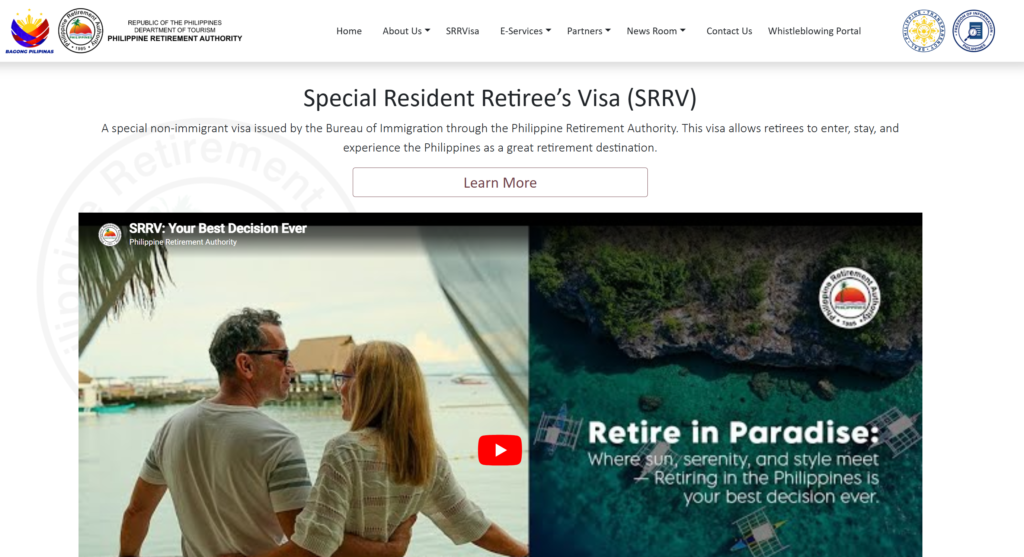
One of the most important is the Special Resident Retiree’s Visa, commonly known as the SRRV.
The SRRV is a special non-immigrant visa issued through the Philippine retirement program administered by the Philippine Retirement Authority. PRA’s current information describes it as a long-term residence option for qualified applicants, with multiple-entry and indefinite-stay privileges subject to maintaining the applicable requirements.
Under the current expanded SRRV program, principal applicants generally begin at age 40, although eligibility, deposits, documentation, and applicable categories depend on the individual’s circumstances. PRA also maintains current application forms and checklists on its official website.
The SRRV can be attractive to retirees who want a more stable long-term residence arrangement than repeatedly relying on visitor status.
However, it is not automatically the best option for everyone.
Depending on personal circumstances, a retiree may need to compare:
- SRRV
- Tourist or visitor status
- Marriage-based residence options
- Other appropriate immigration categories
A retiree married to a Filipino citizen, for example, may have options that are different from those available to a single foreign retiree.
Immigration rules can change, so applicants should verify current requirements with the Philippine Retirement Authority or Bureau of Immigration rather than relying entirely on social-media posts, friends, or outdated online guides.
For a detailed explanation of SRRV deposits, dependents, documents, fees, and procedures, see our SRRV Philippines 2026: Complete Retirement Visa Guide.
3. Build a Realistic Retirement Budget
One of the most common questions prospective retirees ask is:
How much money do I need every month?
There is no single answer.
A retiree living in a modest condominium in Dumaguete and cooking most meals at home may have a completely different budget from someone living in BGC, eating out frequently, taking Grab every day, and traveling internationally several times a year.
The main expenses generally include:
- Rent or housing costs
- Association dues, if applicable
- Electricity
- Water
- Internet and mobile service
- Food
- Transportation
- Healthcare
- Insurance
- Household help
- Entertainment
- Domestic travel
- International travel
- Visa and documentation expenses
- Emergency expenses
One mistake is to build a retirement budget around only normal months.
Retirement planning should also account for bad months.
A medical procedure, family emergency, international flight, major home repair, or unexpected legal or administrative expense can significantly increase spending.
A better retirement budget therefore has three levels:
Regular monthly expenses + annual irregular expenses + emergency reserve
For a more detailed estimate, see our Cost of Living in the Philippines in 2026 guide.
4. Choose the Right Place to Live
The Philippines offers very different retirement lifestyles depending on location.
Metro Manila
Metro Manila offers some of the country’s strongest access to:
- Major private hospitals
- Specialists
- International restaurants
- Shopping
- International airports
- Business services
- Modern condominiums
- Entertainment
The disadvantage is traffic and generally higher living costs in premium areas.
For someone with complex medical needs or who travels internationally frequently, however, these conveniences may justify the cost.
Cebu
Cebu combines major-city services with comparatively easy access to beaches and island destinations.
It has hospitals, shopping centers, condominiums, international flights, and a sizable foreign community.
Dumaguete
Dumaguete has long attracted retirees interested in a smaller-city atmosphere and slower daily pace.
It also provides access to nearby coastal and island destinations.
Tagaytay
Tagaytay appeals to people who want cooler temperatures while remaining relatively close to Metro Manila.
Baguio
Baguio provides a very different environment from the typical tropical Philippine city.
Its higher elevation and cooler weather may appeal to retirees who struggle with constant heat.
Provincial and Coastal Areas
Smaller towns may offer:
- Lower housing costs
- Less traffic
- More space
- Quieter surroundings
- Easier access to nature
But they may also have more limited:
- Hospitals
- Specialist doctors
- International food
- Transportation
- Banking
- Government services
- International airport access
This is why the cheapest location is not always the best retirement location.
5. Rent Before You Buy
One of the most useful pieces of advice for newcomers is simple:
Rent first.
There is rarely a need to buy a property immediately after arriving.
Living in a neighborhood for several months reveals things that a property viewing cannot.
You begin to understand:
- Traffic
- Noise
- Building management
- Internet reliability
- Water pressure
- Elevator waiting times
- Flooding risks
- Supermarket access
- Hospital access
- Parking
- Neighborhood safety
- Delivery services
- Actual travel times
A beautiful condominium may look perfect during a one-hour viewing.
Six months later, you may discover that the elevators are constantly crowded, traffic outside the building is terrible, or the nearest hospital is inconvenient.
Renting gives you time to learn.
It also gives you the freedom to change cities if your first choice turns out to be wrong.
For newcomers considering Metro Manila, our Condo Living and Transportation in Manila for Newbies guide explains these issues in greater detail.
6. Plan for Healthcare Before You Need It
Healthcare planning becomes increasingly important during retirement.
A healthy retiree may initially think very little about hospitals.
That can change quickly.
The important question is not simply:
Does the Philippines have good hospitals?
The better question is:
How quickly can I reach the medical care I may personally need?
Before choosing a permanent location, investigate:
- Nearest major hospital
- Emergency department
- Cardiologist
- Orthopedic specialist
- Oncologist
- Ophthalmologist
- Dentist
- Pharmacy
- Diagnostic facilities
- Ambulance availability
- Travel time during traffic
A healthy 55-year-old may be perfectly comfortable living far from a major urban center.
The same person at 75 may value hospital access much more highly.
Foreign retirees should also investigate private insurance and other available healthcare coverage before relocating. PhilHealth has provided coverage mechanisms for certain foreign nationals and former Filipino citizens who retire in the country, but eligibility, premiums, and benefits should be checked against current rules rather than assumed.
Healthcare should influence where you live, not become something you consider only after becoming ill.
7. Decide How You Will Get Around
Transportation can have a surprisingly large effect on retirement quality.
Depending on location and lifestyle, retirees may use:
- Grab
- Taxis
- Public transportation
- A private car
- A hired driver
- Walking
- A combination of several options
Someone living in BGC may be able to walk to supermarkets, restaurants, parks, and medical clinics.
Someone living in a suburban or provincial area may consider a car essential.
Vehicle ownership provides convenience but creates additional costs:
- Purchase price
- Fuel
- Insurance
- Registration
- Maintenance
- Repairs
- Toll fees
- Parking
A driver can make daily life easier but also introduces salary, employment obligations, scheduling, and personnel management.
Transportation should therefore be included in the retirement budget together with housing.
A cheaper home far from everything you use regularly may eventually cost more—in both money and time—than a more expensive home in a convenient location.
8. Plan Your Banking and Money Transfers
Retirees need a reliable way to access money.
Before relocating, think about how retirement income will move between countries.
Questions to consider include:
- Where will my pension be paid?
- Will I keep my primary bank account in my home country?
- Do I need a Philippine bank account?
- How will I transfer money?
- What exchange-rate costs will I pay?
- What happens if my foreign credit card is blocked?
- How will I access emergency funds?
- Do I have more than one payment method?
Do not rely on only one bank account or one credit card.
International banking problems can happen at inconvenient times.
A safer setup may involve:
- A primary overseas account
- A Philippine account where appropriate
- More than one credit card
- An emergency cash reserve
- Secure online banking access
- A backup method for international transfers
Bank account requirements vary between institutions and according to residency and identification status, so retirees should confirm the current documentary requirements directly with their chosen bank.
9. Understand Property Ownership Before Investing
Foreign retirees need to understand an important distinction in Philippine property law:
Owning a condominium and owning land are not the same thing.
Foreign ownership of Philippine real estate is subject to constitutional and statutory restrictions.
Condominium ownership can be available to foreigners subject to applicable legal limitations, while direct land ownership is generally much more restricted.
Foreign buyers should therefore avoid assuming that buying property works exactly as it does in their home country.
Before investing, investigate:
- Legal ownership structure
- Foreign ownership restrictions
- Title
- Developer reputation
- Association dues
- Taxes and transaction expenses
- Resale market
- Building management
- Rental potential
- Inheritance implications
Property should be treated as a major investment decision, not simply part of the excitement of moving abroad.
10. Prepare for Insurance and Emergencies
Retirement planning should include situations you hope never happen.
An emergency fund can help cover:
- Medical treatment
- Emergency flights home
- Family emergencies
- Major property repairs
- Legal expenses
- Unexpected relocation
- Temporary accommodation
- Currency movements
- Delays in pension or investment income
How large the emergency fund should be depends on individual circumstances.
A person with extensive international health insurance and several stable income sources may need a different reserve from someone relying primarily on one monthly pension.
The important principle is to keep emergency money accessible.
A property worth millions of pesos does not help much if you suddenly need cash tomorrow.
11. Think About Your Family Situation
Retirement decisions rarely affect only one person.
If you have a spouse or dependents, consider:
- Their immigration status
- Healthcare
- Housing needs
- Education, if children are involved
- Travel
- Family relationships
- Estate planning
- Financial dependence
Mixed-nationality families may face additional questions involving residency, property, inheritance, and citizenship.
These matters should be considered before large assets are purchased or moved across borders.
12. Build a Life, Not Just a Retirement Location
This is one of the most overlooked parts of retirement planning.
What will you actually do every day?
A person may dream for years about retiring beside the sea.
After six months, waking up beside the sea every morning may become normal.
Retirement can last decades.
A sustainable retirement life may include:
- Exercise
- Golf
- Volunteering
- Church or community activities
- Language study
- Photography
- Travel
- Gardening
- Reading
- Part-time consulting
- Digital projects
- Business
- Friends
- Family activities
Some retirees eventually decide to start small businesses or consulting activities because they want purpose and intellectual stimulation rather than simply additional income.
If that interests you, see our guide to 10 Best Businesses Retirees Can Start in the Philippines.
Retirement should not simply answer the question:
Where will I live?
It should answer:
What kind of life will I build there?
13. Test the Lifestyle Before Making a Permanent Move
If possible, spend an extended period in the Philippines before making major commitments.
Do not treat this period like a vacation.
Live normally.
Rent an ordinary condominium or house.
Buy groceries.
Cook.
Use Grab.
Visit a hospital.
Walk around the neighborhood.
Experience traffic.
Experience rain.
Pay electricity bills.
Use the internet.
Visit government offices if necessary.
Try living through ordinary weekdays.
You may discover that a place you loved on vacation does not suit everyday life.
You may also discover that a city you had never seriously considered fits you perfectly.
Testing the lifestyle is far cheaper than discovering a mistake after buying property and moving your entire life overseas.
Practical Retirement Preparation Checklist
Before making a long-term move, try to answer every question in this checklist.
| Area | Questions to Answer |
|---|---|
| Visa | What immigration status will allow me to stay long-term? |
| Budget | What is my realistic monthly spending limit? |
| Income | How reliable are my pension, savings, investments, or other income sources? |
| Healthcare | Which hospitals and specialists will I use? |
| Insurance | What medical and travel coverage will I maintain? |
| Housing | Where will I rent first? Would I eventually buy? |
| Location | How close am I to hospitals, shops, airport, friends, and family? |
| Transportation | Will I rely on Grab, public transport, a car, or a driver? |
| Banking | How will I receive and transfer money? |
| Emergency fund | How much accessible cash should I keep available? |
| Family | Will my spouse or dependents move with me? |
| Daily life | What will I actually do during normal weeks? |
| Property | Do I understand foreign ownership restrictions? |
| Documents | Which documents need apostille, authentication, or translation? |
| Exit plan | What happens if I later decide to leave the Philippines? |
Do Not Forget an Exit Plan
An exit plan may sound strange in an article about preparing to retire in the Philippines. But it is an important part of responsible planning.
Circumstances change. Health can change. Family members may need you back home. Exchange rates can move. Political or economic conditions can change.
You may simply decide after ten years that you want something different.
Ask yourself:
- Could I sell my property easily?
- Where would I go if I needed advanced medical treatment?
- What happens to my belongings?
- What happens to my visa deposit?
- Can I maintain financial accounts in both countries?
- Does my family know where important documents are?
- What happens if I become unable to manage my affairs personally?
Planning for these possibilities does not mean expecting retirement to fail.
It simply means keeping options open.
How the SRRV Fits Into the Bigger Retirement Plan
The SRRV is important, but it should not become the entire retirement plan.
A visa solves one major issue:
the legal ability to remain in the country under the conditions of that visa.
It does not automatically solve:
- Housing
- Healthcare
- Monthly expenses
- Transportation
- Banking
- Insurance
- Social life
- Family issues
- Property decisions
The Philippine Retirement Authority administers the SRRV program and maintains current application forms, checklists, and applicant information. Applicants should use those official materials when preparing an application because requirements can change over time.
Think of the SRRV as one part of a larger retirement structure.
The strongest retirement plan combines:
Legal residency + sustainable finances + suitable housing + healthcare access + meaningful daily life + flexibility for the future.
Final Thoughts
Preparing for retirement in the Philippines is not simply about deciding whether you like the country. It is about determining whether you can build a sustainable life there.
The beaches matter. The weather matters. The food matters. The lower cost of certain aspects of life may matter.
But over a 20- or 30-year retirement, practical considerations become increasingly important.
Where will you receive medical treatment?
How will you access your money?
What happens when you can no longer drive?
Can you afford your lifestyle if prices rise?
Will you still enjoy your location after the excitement of moving disappears?
Do you have friends, family, hobbies, or meaningful activities?
And if circumstances change, can you change your plan?
A successful retirement does not require predicting everything perfectly.
It requires leaving enough flexibility to adapt.
Choose carefully. Rent first. Understand your visa. Protect your finances. Plan for healthcare. Test the lifestyle. Then make the bigger commitments.
That approach may not be as exciting as choosing a beach house from a photograph.
But it is much more likely to produce a retirement in the Philippines that still feels right many years later.
Leave a Reply